ع


Kuwait’s move to machine-readable financial statements puts the quality of everyday bookkeeping in focus, with Alliance among the advisers preparing businesses for the change.
Kuwait’s shift towards electronic financial reporting is approaching a defined deadline. The government has set the beginning of 2027 for mandatory implementation of its Qayd system, following a transition period during 2026.
For business owners, the change is more substantial than replacing a paper document with an uploaded file. Qayd uses XBRL, a format that turns financial statements into structured information that software can read and compare. That makes the quality of the records behind the final submission an important part of the transition.
Alliance, a Kuwait business consultancy, is already positioning its bookkeeping work around that requirement. Its preparations provide a local entry point into a wider question: what happens when the financial information produced by a small business must satisfy a more structured reporting process?
A deadline with a different kind of data
In its January 2026 statement, Kuwait’s Cabinet described the move towards electronic financial-statement submission and the adoption of XBRL. The stated objectives included improving data quality, supporting comparisons across companies and sectors, and developing a national financial database.
The transition was also described in April reporting on the ministry’s launch of the enabling phase. Electronic filing was optional during 2026, while existing submission arrangements remained required. The announcement identified 1 January 2027 as the start of mandatory electronic filing using XBRL.
Those dates distinguish a preparation period from the eventual requirement. They also explain why work on underlying records belongs before the deadline. A business does not create an accurate financial history simply by reaching the point at which a report must be submitted.
The government’s objectives concern the reporting system as a whole. Preparation still involves accounting judgements about the transactions being recorded. Reconciliations connect entries in the accounts with external records such as bank statements, while classifications determine where amounts belong in the eventual financial report. The format changes how information can be handled; the information still has to be prepared correctly.
What machine-readable reporting changes
XBRL International, the organisation responsible for the standard, describes a system in which business concepts are represented using a common digital structure. Taxonomies define the reporting vocabulary, allowing software to recognise what individual facts mean.
A scanned statement may be readable to a person while remaining difficult for a computer to analyse reliably. Structured reporting adds meaning to the figures, including the concepts and periods they represent. That is what permits comparisons without treating every document as a separate manual extraction exercise.
The distinction helps explain why digital filing is not interchangeable with ordinary document storage. Saving a balance sheet as a PDF preserves its appearance. Preparing a structured report makes its information available in a form designed for systematic use.
It also brings consistency into view. Figures that refer to different periods or categories cannot be meaningfully compared simply because they sit next to one another in a file. The reporting structure needs to preserve those distinctions. For businesses, the practical consequence is that classification and reconciliation become part of preparing usable data, rather than only producing an attractive final statement.
The local advisory work behind the filing
Alliance’s published service information describes bookkeeping and finance management that includes monthly reconciliations, management accounts and preparation for the Qayd and XBRL transition. These are company-described services, not evidence that any particular client has completed the process or achieved a financial result.
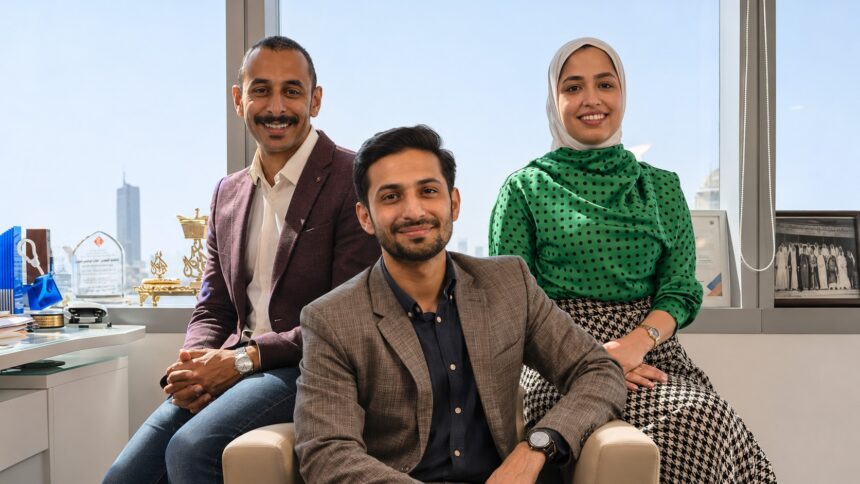
The consultancy’s account of its own formation says it emerged in 2019 after experience in Cubical Services’ SME division. Its team includes founder and chief executive Ismail Johar, co-founder Salem Al-Mutawa in operations and business planning, and co-founder Khawla Atyani in government relations.
The combination is relevant because business records are produced through everyday operations. Sales, purchasing, payroll and other transactions occur before the financial statements are prepared. Work on those records therefore connects administrative routines with the information eventually used for reporting.
The same records also serve a different audience: the owner. Management accounts and reconciliations can explain discrepancies between a business’s recorded activity and its cash position. That is a separate purpose from regulatory submission, even when both rely on the same underlying transactions.
Profit, cash and the reporting trail
A reported profit and money available in the bank answer different questions. Revenue may be recognised before a customer pays. Cash may be spent on an asset whose cost is reflected in accounts over time. Borrowing can increase the bank balance without representing sales income.
These are basic accounting distinctions, but they illustrate why a filing requirement cannot be separated entirely from day-to-day record keeping. A company needs to know what a transaction represents before it can classify and report it consistently. A higher sales total alone does not explain collections, liabilities or the timing of expenditure.
For advisers such as Alliance, the impending change creates work around that connection between operational records and formal reporting. For the businesses concerned, the immediate issue is more concrete than a broad promise of digital transformation: whether the information needed for submission is complete, reconciled and organised in the required form.
The deadline is now approaching. The test of preparation will be the quality of the financial information submitted through Qayd, and whether the records behind it support the figures that the system receives.